1kredit.kz - collateral lending
A lead channel for a lender: 1,265 applications in 11 months at ~$7.60, CTR ~8.8% against a 2-5% niche benchmark - and $53 in loans issued for every $1 of ad spend
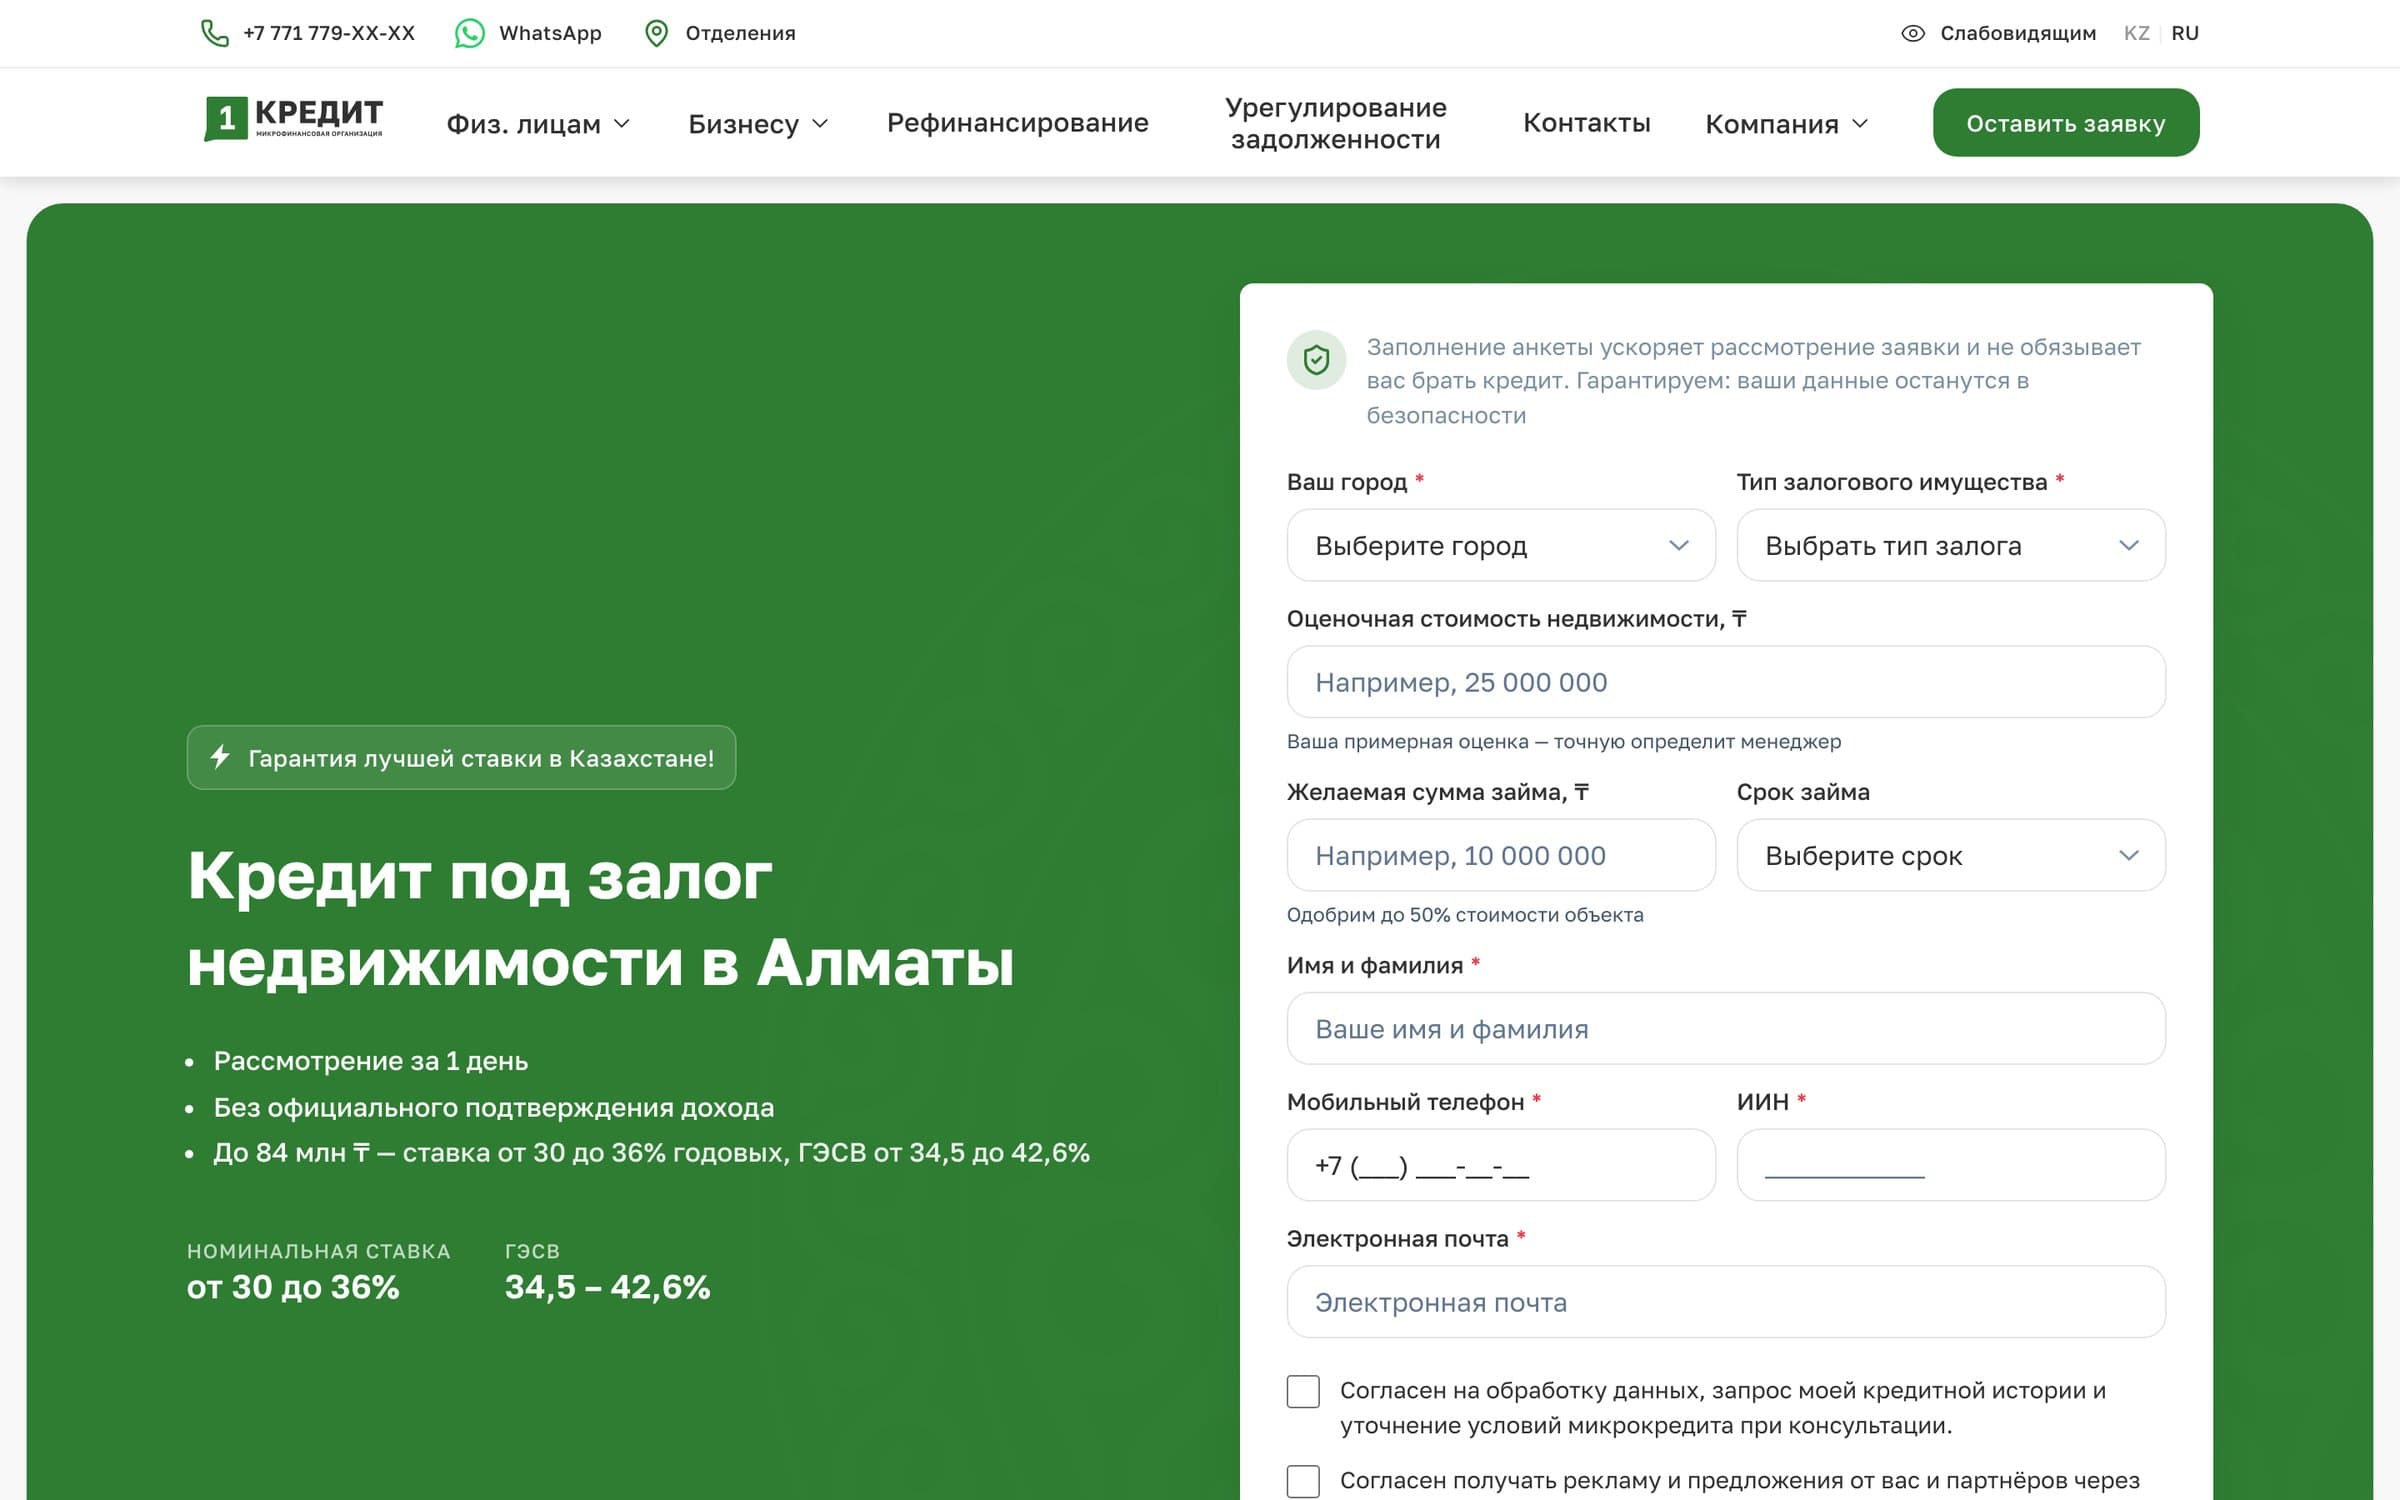
Under the contract of 07.06.2024 we run marketing and development for a collateral lender: website and landing pages, paid search, CRM and automated scoring. From August 2025 to June 2026 Google Ads across 5 regions plus dedicated landing pages produced 1,265 applications at ~$7.60 each, with CTR 1.8-4.4 times above the benchmark for the niche. Most of the volume comes from property-backed loans; on the car-backed pilot we are lifting the operational ceiling - CRM, automated scoring, automated collateral valuation and a bank statement parser are live, the integrations with both credit bureaus (GKB and PKB) went into production in May 2026, and the automation rolls out to every product next.
- Industry
- Fintech · microfinance, loans against property and cars
- Location
- Kazakhstan · Almaty, Astana, Shymkent, Aktobe
- Profile
- Lender with 15 years on the market · 8 branches in 4 cities · ~3,800 clients
- Timeline
- Since June 2024 (contract of 07.06.2024)
Challenge
A lender with 15 years on the market and 8 branches in 4 cities needed an online lead channel for its collateral products: a website that collects applications and paid search for the product. On top of that everything was manual - a manager called the client, the client had to come to the office, credit bureau scoring and collateral valuation happened outside any system, at the manager's discretion. The job was to build the lead channel and remove the operational ceiling in parallel.
Strategy
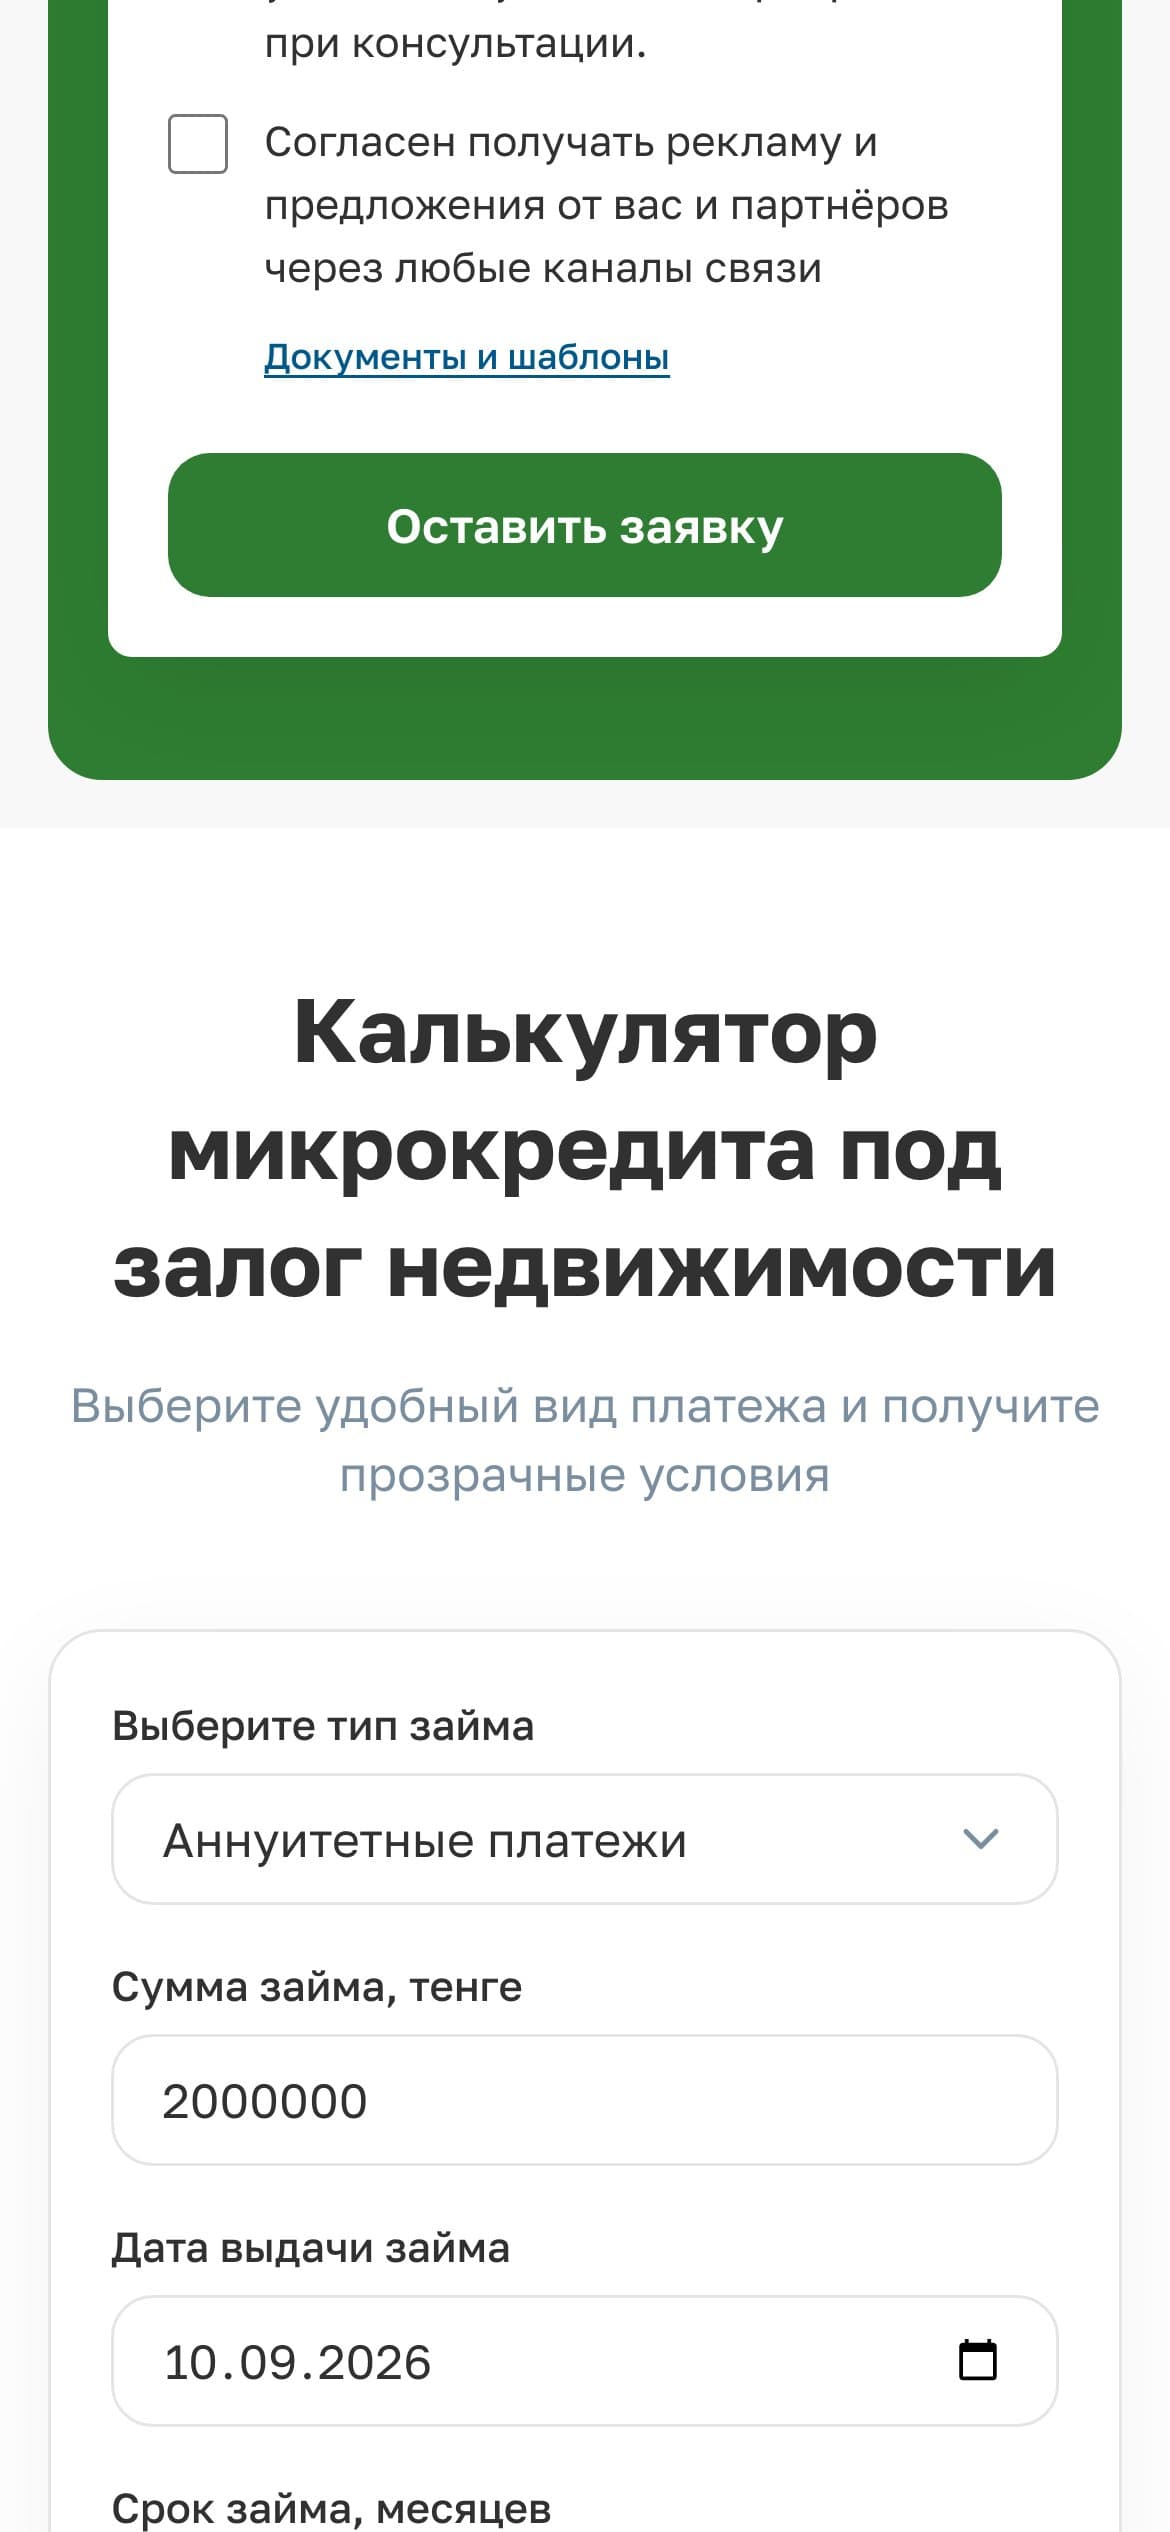
We built and proved the marketing channel: a corporate website, landing pages for the property-backed and car-backed products, and paid search, moving the site off Webflow onto a custom stack for full control over SEO factors; the 2026 version of the site runs in Russian and Kazakh. In parallel, on the car-backed pilot product, we deployed CRM, automated scoring, automated collateral valuation and a bank statement parser, and the credit bureau integrations (GKB and PKB) went into production in May 2026 - to lift the operational ceiling and then roll the automation out across every product.
- Manual calls and a mandatory office visit - a long path from application to payout, with drop-off at every step
- Borrower scoring against the credit bureau and the state population register - separate requests outside the system, slow and without a standard
- Collateral valued at the manager's discretion, with no single rulebook and no scoring model
- No CRM: applications lived in spreadsheets and messengers, statuses and deal history got lost
- 1C was isolated from the website and the ad accounts - there was no end-to-end view from lead to payout
In lending, marketing brings the application, but the money is made by the speed of processing it. No matter how many leads you pour in, as long as a decision needs an office visit and manual scoring, the flow hits an operational ceiling. So first we prove and scale the channel, and in parallel we remove the ceiling with technology - on one product first, then on all of them.
What we did, by channel
- Paid search since 2024; the case numbers are Google Ads for August 2025 - June 2026
- Google Ads Search across 5 regions: Almaty, Astana, Shymkent, Aktobe and the surrounding areas
- Most of the campaign volume goes to property-backed loans; a separate Almaty - Car campaign covers car-backed loans
- Ads served only on collateral-specific queries - cutting off the flow of unsecured loan requests you would otherwise pay for
- Optimized for cost per application, not clicks: CPL ~$7.60, average landing page conversion into an application 25%
Why: Keeping traffic clean in this niche is hard: unsecured loan leads are everywhere and you pay for them. We show up only on collateral queries, which is why CTR runs above the 2-5% benchmark for the niche and the applications are ready to buy, converting at around 25%.
- Corporate website and landing pages built for the ad campaigns
- Migration from Webflow to a custom stack - full control over SEO factors and speed
- Structure and forms built around the collateral loan application
- 2026 version of the site: Russian and Kazakh (KZ) versions
Why: Webflow limited control over the technical SEO base. A custom stack removes the ceiling on speed and ranking factors - for organic growth over the long run.
- Started right after the site moved to the custom stack
- Automated article pipeline: query clustering in Serpstat → generation → publishing
Why: Paid search delivers applications immediately but gets more expensive as competition grows. Organic lowers the average cost per application over time and does not depend on bids, and the article pipeline scales coverage of the keyword space.
- CRM as a single application pipeline: intake, statuses, deal management (live)
- Automated borrower scoring and automated collateral valuation (live)
- Bank statement parser for automatic income verification (live)
- Credit bureau integrations (GKB and PKB) - in production since May 2026; export to 1C for the credit committee - next in line
Why: The car-backed product is the pilot where we launched the automation and the integrations. The goal is a remote decision on an application and a rollout across every product of the lender, including property-backed loans.
A closer look
Project numbers
The metrics are real; some are under NDA and shown in a call.
What did not work and the risks
The decisions we rejected and the risks we planned for in advance.
- Most of the application volume comes from the property-backed product; car-backed is smaller and serves as the pilot for the fintech automation
- Part of the campaigns is capped by budget and ad moderation (limited by budget, ads disapproved) - there is headroom once those limits are lifted
- SEO started only after the site migration, so organic is still building up and paid search still carries the main flow
- The real ceiling right now is not marketing but manual processing: until the automation proven on the car-backed product is rolled out, volume on the rest is limited by the speed of manual scoring
Takeaway
We built a channel that brings the lender about 120 applications a month and returns $53 in loans issued for every $1 put into advertising, at a CTR 1.8-4.4 times above the benchmark for the niche. The automation is proven on the car-backed pilot - the next step is to roll it out across every product, including property-backed loans, and make the decision fully remote, with no office visit.
Next case
Let's see what from this case will work for you
We show where you lose clients on your own numbers and lay out a plan for a steady flow of leads.
The audit is free and comes with no obligations.